Headline GDP growth of 4.5% in China during the third quarter of 2026 does not signal a broad economic rebound; it reveals a bifurcated machine where external hardware demand props up an economy weighed down by sluggish domestic spending.
Standard headlines treat a beat against consensus forecasts—4.5% year-on-year expansion after 4.3% in the second quarter—as proof of momentum. That reading mistakes a narrow export surge for generalized vitality. Across the first nine months of 2026, gross domestic product rose 4.6%, keeping authorities inside their annual target band of 4.5% to 5%. Yet beneath that aggregate sits a sharp split between export-oriented manufacturing and domestic balance sheets.
Competitor reporting typically maps this story along a thin linear chain: third-quarter growth beat expectations, exports jumped, and therefore the economy is recovering. That logic skips the structural mechanics. It treats net external demand as a substitute for household absorption, glosses over steep contractions in fixed-asset and property investment, and leaves unanswered whether overseas orders for electronics and AI-linked hardware can carry the entire system over time.
Deconstructing the Competitor Narrative
Conventional coverage compresses a complex macro adjustment into a single number. When a headline declares that growth quickened to 4.5% as exports surged, it implies balanced acceleration across sectors. In reality, aggregate GDP is an accounting identity: consumption, gross capital formation, and net exports move on distinct timetables and respond to different incentives.
Three analytical blind spots weaken standard summaries of this release:
- Aggregation bias: Combining fast-growing hardware shipments with contracting property investment and slow retail goods sales averages out two opposing forces. A rising headline rate does not mean broad-based firm profitability or rising household confidence.
- Confusing cyclical beats with structural repair: Beating a narrow consensus estimate by a fraction of a percentage point reflects short-term forecast error and trade timing, not a resolution of property overhang or weak domestic final demand.
- Ignoring transmission lags: Export orders and industrial output show up immediately in factory activity and customs tallies, whereas balance-sheet repair and wage-led consumption adjust slowly.
Distinguishing between known facts and educated hypotheses keeps the analysis grounded. Known facts from official data include the 4.5% third-quarter year-on-year GDP reading, the 1.2% quarter-on-quarter gain, the 4.6% expansion over the first three quarters, rapid export expansion led by mechanical, electrical, and tech-related goods, and sharp weakness in property development investment and retail goods sales. Educated hypotheses include whether global AI hardware demand will remain elevated enough to offset domestic softness into 2027, and how quickly targeted fiscal and housing measures can shift household spending behavior.
The Two-Speed Growth Architecture
To understand why the third quarter printed 4.5% while domestic demand stayed subdued, view the economy through a two-speed architecture: an External Hardware Engine operating at high velocity alongside a Domestic Absorption Drag working in the opposite direction.
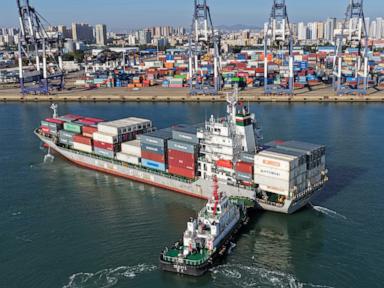
In national accounts, export surges lift output when domestic supply chains capture value from foreign capital spending. Global demand tied to computing infrastructure, electronics, batteries, and industrial equipment has pulled export volumes sharply higher—with September goods exports jumping 36.3% year-on-year in dollar terms (and 29.6% in yuan terms)—boosting industrial value added and keeping factory utilization elevated. High-tech and equipment manufacturing have acted as primary shock absorbers against domestic weakness.
Consider a precision electronics assembly hub in coastal South or East China. When overseas data-center and device buyers place large orders, component suppliers, contract manufacturers, and logistics operators run extra shifts. Ports clear cargo, customs revenues and trade surpluses widen, and industrial output rises. Yet factory margins face fierce price competition, overtime pay may not translate into broad retail splurges, and inland provinces tied to traditional construction see far less of that windfall.
Domestic absorption faces structural headwinds that export growth alone cannot cure:
- Property wealth and investment contraction: Real estate development investment fell 20.6% over the first nine months of 2026, dragging overall fixed-asset investment down 7.2% across the same period. Because housing sits at the center of household net worth and local land-related finances, ongoing contraction weighs on both builder capital spending and consumer confidence.
- Muted goods consumption: Retail sales of goods rose just 1.1% in the first nine months and in September, while services spending has shown firmer relative traction. Households are pacing outlays carefully rather than staging a broad goods-led spending boom.
- Supply-demand imbalance: Strong industrial production paired with soft domestic demand keeps pricing power constrained across many consumer and intermediate categories, risking margin compression when export growth eventually normalizes.
Cause-and-Effect Chains Standard Coverage Misses
Competitor summaries often list export strength and weak domestic indicators side by side without connecting the causal loops between them. In an open industrial economy undergoing balance-sheet adjustment, these linkages run through specific channels.
The External Demand and Trade Policy Loop
Surge dynamics in trade depend heavily on product mix and trade frictions. High-growth categories such as mechanical and electrical products, industrial automation, batteries, and electronics reflect global capital expenditure cycles. When foreign buyers accelerate hardware orders, Chinese exporters gain volume. At the same time, rising trade surpluses and concentrated export growth heighten sensitivity to tariffs, customs rules, and supply-chain diversification by trading partners. A spike in a single quarter's export growth rate—especially one as sharp as September's—can reflect order front-loading, seasonal timing, or base effects rather than a permanent step-change in trend growth.
The Policy Calibration Constraint
A 4.5% growth print that beats consensus creates a subtle policy dilemma for Beijing. When headline GDP sits right at the lower bound of the 4.5% to 5% annual goal and exports are booming, policymakers face less immediate pressure to deploy massive, indiscriminate stimulus. Measures such as mortgage subsidies, targeted rate adjustments, and allocating 550 billion yuan from unused debt quotas to ease local government strain and support infrastructure aim to stabilize floor activity without reigniting speculative real estate bubbles.
The second limitation of relying on incremental targeted measures is timing. Local fiscal relief and housing incentives work through multi-quarter channels: project approvals, construction starts, debt rollovers, and household sentiment adjustments take time to materialize. If authorities hold back broader demand support because headline GDP looks acceptable, domestic demand can stay sluggish longer than expected. Conversely, overly aggressive credit stimulus risks rebuilding debt overhang in sectors already working off excess capacity.
The Cost Function of Export Reliance
Every growth model carries an implicit cost function. Leaning heavily on external demand lowers short-term GDP volatility during domestic slumps, but it raises exposure to three compounding costs:
- External cycle risk: Overseas capital spending on tech hardware and industrial equipment is inherently cyclical. Any slowdown in global corporate tech budgets or shifts in trade barriers directly cool export momentum.
- Regional and sectoral divergence: Gains concentrate in advanced manufacturing clusters, coastal logistics hubs, and supply chains linked to global trade, widening performance gaps against domestically oriented businesses and lagging regions.
- Deflationary pressure on tradables and domestic goods: When domestic absorption lags industrial capacity, producers competing for market share face downward price pressure, squeezing corporate cash flows needed to fund wages and domestic investment.
Operational Playbook for Executives and Allocators
Operators, supply-chain leaders, and capital allocators cannot manage against a headline GDP figure alone. Decisions require segmenting exposure by end-market demand, balance-sheet resilience, and policy alignment.
Follow this four-step diagnostic sequence when evaluating exposure or planning operations:
- Audit revenue by final payer, not shipment origin. Separate sales tied to overseas corporate capital expenditure and global tech supply chains from sales dependent on Chinese household discretionary budgets or property developers. Do not assume domestic demand will automatically follow export strength.
- Stress-test unit economics against price compression. Model operating margins under flat or slightly softer selling prices rather than assuming inflation will bail out volume growth. Prioritize cost discipline, inventory turnover, and supplier payment terms over capacity expansion in crowded segments.
- Track policy execution rather than announcements. When authorities roll out targeted rate tweaks, housing support, or local debt quota allocations, monitor actual disbursement pace, local government project execution, and credit uptake rather than headline program size.
- Build optionality across trade corridors. For cross-border operators, maintain flexible sourcing, dual-market compliance readiness, and buffer lead times so a sudden shift in tariffs, shipping rates, or overseas order schedules does not halt production.
No single analytical framework eliminates uncertainty. Official macro statistics undergo revisions, trade figures can swing sharply from month to month, and policy shifts can alter domestic sentiment faster than econometric models anticipate. Treat these steps as risk-management guardrails, not guarantees.
Strategic Play
Treat the third quarter's 4.5% growth reading as a bridge quarter, not a signal to relax domestic caution. For commercial leaders and capital allocators, the decisive move over the next two quarters is to harvest cash flow from resilient high-tech and export-linked value chains while keeping domestic consumer and property-linked exposure tightly hedged until household spending growth accelerates sustainably beyond sluggish goods-sales baselines.