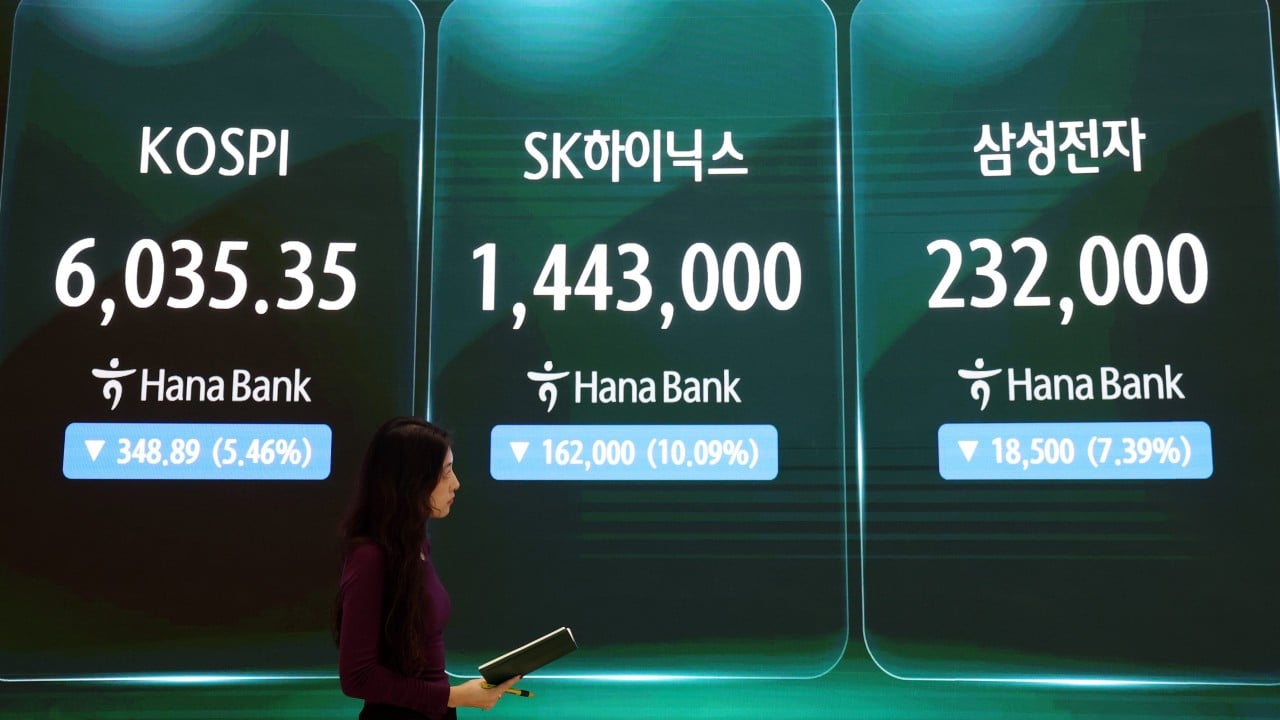
You would think printing billions in profits would keep a stock price happy. Yet, memory giants like Samsung and SK Hynix have watched their valuations take painful hits, even as the global appetite for artificial intelligence hardware stays hot. If data centers are gobbling up every high-bandwidth memory chip they can find, why are investors panicking?
The disconnect between record financial performance and jittery market sentiment comes down to a few uncomfortable truths about how the semiconductor industry actually works. Let's look past the hype and examine why the market is sweating over the current chip boom.
The Overcapacity Ghost and the China Factor
Everyone is talking about AI demand, but memory manufacturing is a cyclical beast. When prices for specialized chips surge, every major player floods capital expenditure budgets into new fabrication plants. Samsung recently ramped up its chip capital spending by roughly 60 percent, while SK Hynix is aggressively expanding its packaging lines.
At the same time, domestic Chinese competitors like ChangXin Memory Technologies (CXMT) are making rapid strides. While CXMT is still largely concentrated on standard DRAM and mobile memory rather than the cutting-edge High Bandwidth Memory (HBM) required for elite AI accelerators, its global DRAM revenue share climbed toward 9 percent.
Wall Street worries about a classic supply glut. When legacy and mainstream memory lines fill up, pricing power tends to evaporate quickly. Investors aren't pricing in today's stellar earnings report; they are trying to figure out what happens when the factory buildout catches up to current demand around 2027.
Speculation Fatigue and Margin Pressures
Another major weight on these stocks is valuation fatigue. Markets spent months treating AI hardware suppliers as an endless upward escalator. When major industry voices start warning that tech infrastructure spending resembles high-stakes gambling, institutional money gets twitchy.
Even though SK Hynix posted massive multi-hundred-percent profit surges and Samsung smashed records with a historic quarterly operating profit, share prices dropped sharply during sector-wide selloffs. Why? Because peak earnings often signal that things can only get more expensive to maintain. Building advanced 3D-stacked memory requires staggering capital investments, and any sign of a spending slowdown from hyperscale cloud providers sends shockwaves through Seoul and New York.
Navigating the Volatility
If you're watching these semiconductor stocks or trying to understand where the hardware cycle goes next, you have to separate short-term market panic from structural reality.
- Look past the headline profits: Record quarters are lagging indicators. Pay closer attention to capital expenditure guidance and inventory turnover rates.
- Watch the packaging bottleneck: The real constraint for AI memory isn't just silicon production—it's advanced packaging capacity like TSV (through-silicon via) technology. Whichever firm solves yield issues here keeps its pricing power.
- Monitor non-AI segments: Consumer electronics and traditional PC demand still account for a huge chunk of baseline memory consumption. If those sectors stay sluggish, commodity price drops can drag down overall margins.
The AI supercycle is real, but equity markets hate uncertainty. Until investors get clarity on long-term capital spending sustainability and regional supply competition, even the most profitable chipmakers will keep riding a roller coaster.