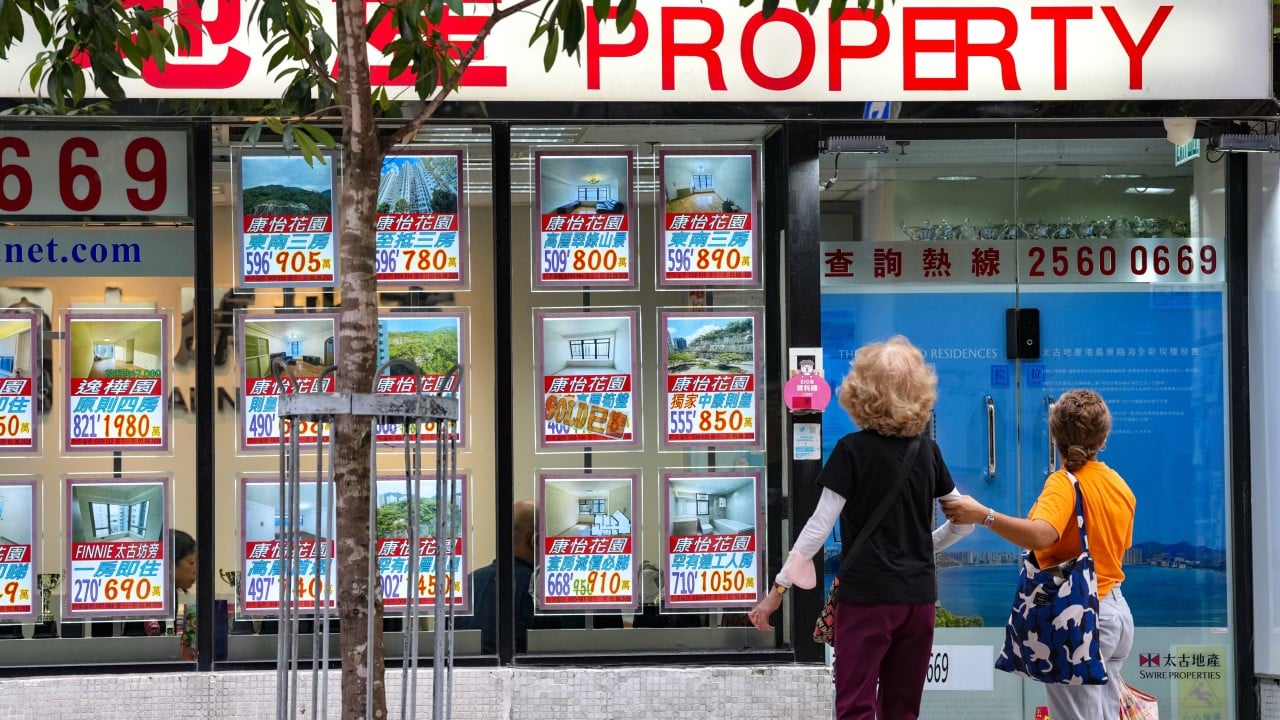
Property market indicators in Hong Kong tell a contradictory story. Official metrics attempt to project stability while real-world transactions reveal continued distress. Recent market data shows an uptick in residential sales finalized at significant financial losses, even as brokerage reports and government commentary insist the broader price correction has bottomed out. This divergence exposes a market caught between psychological relief and hard financial pressure.
Sellers are cutting losses because holding vacant property carries compounding costs. Mortgage rates remain elevated compared to the near-zero era that fueled the previous decade's speculative buying frenzy. When a property fails to generate rental income sufficient to cover debt servicing, landlords face a stark choice. They can absorb monthly cash flow deficits or offload the asset at a nominal loss to eliminate the liability. Many are choosing the latter, creating a shadow supply of discounted units that official index tracking often struggles to capture in real time. Discover more on a similar subject: this related article.
Real estate agents on the ground report a steady stream of secondary market transactions where previous owners take haircuts ranging from ten to thirty percent relative to purchase prices from prior peaks. These are not distressed bank seizures in every instance, but rather calculated exits by investors seeking liquidity or professionals relocating overseas. The persistence of these loss-making deals demonstrates that buyer confidence remains fragile. Optimistic headlines about transaction volumes returning do not automatically translate into pricing power for individual sellers.
The Mechanism of Disconnect
Economic indicators in real estate frequently suffer from a lagging design. Transaction indices aggregate completed sales over multi-week windows, smoothing out volatility. By the time a quarterly index registers a downward shift, the transactions driving that shift occurred months prior. Conversely, when prices bounce off a theoretical floor, the first wave of movement typically involves highly motivated sellers clearing inventory at discounted rates to test buyer depth. Further reporting by Reuters Business explores related perspectives on the subject.
Liquidity dynamics explain why losses continue to mount despite stabilizing sentiment. During market downturns, volume dries up before prices fully adjust. Sellers hold out for historical benchmarks, and buyers sit on the sidelines waiting for deeper discounts. When trading finally resumes, it does so at clearing prices that reflect current borrowing costs rather than nostalgic valuations. Every discounted transaction resets the local comparable sales baseline, forcing subsequent sellers to match those lower figures if they hope to secure a buyer.
Financial Pressures and Mortgage Realities
Financing structures in the territory amplify these pressures. Many buyers who entered the market near the 2021 peak utilized high loan-to-value ratios or developer second-mortgage schemes that have since reset to higher market interest rates. As monthly mortgage payments consume a larger share of household income, financial strain accumulates.
Consider a hypothetical buyer who purchased a flat in the New Territories for eight million Hong Kong dollars during the peak years, putting down ten percent. With subsequent market adjustments and sustained high interest rates, refinancing options narrow. If personal cash flow tightens due to macroeconomic headwinds or sector-specific job market contractions, the debt burden becomes unsustainable. Selling at a seven million dollar valuation means swallowing a one million dollar principal loss alongside transaction taxes and agent commissions, yet it stops the bleeding.
Broader Economic Implications
The willingness of owners to absorb losses signals a shift in market psychology. For years, the prevailing belief was that property values in the region possessed an implicit government-backed floor due to severe geographical constraints and housing shortages. That dogma is being tested by reality. While structural supply constraints remain a long-term factor, short-term affordability limits and demographic shifts exert downward force.
Institutional investors and individual homeowners alike are re-evaluating yield versus risk. Alternative asset classes, including fixed-income instruments yielding attractive returns without maintenance headaches, compete directly with residential real estate for capital. When rental yields hover near two percent while borrowing costs sit significantly higher, the math of property ownership ceases to favor passive appreciation.
Market bottoms are rarely a single moment in time; they are extended zones of volatility where distress and recovery overlap. As long as carrying costs outpace expected capital growth for secondary properties, loss-making transactions will remain a persistent feature of the landscape, serving as a truer barometer of market health than corporate PR releases or optimistic brokerage forecasts.