Capital formation within specialized financial hubs relies entirely on the continuous transmission of capital from early-stage risk-bearers to public market exit vehicles. When regulatory friction accumulates at the intersection of private venture creation and public exchange listing, the entire ecosystem experiences liquidity contraction. Recent assessments from trade organizations such as the Federation of Hong Kong Industries (HKEIA) regarding Hong Kong's market infrastructure point to a structural misalignment: while public equity mechanisms have undergone targeted calibration, the primary-market seed and angel funding tiers remain
Structural Mechanics of Equity Capital Access in Hong Kong Markets
business
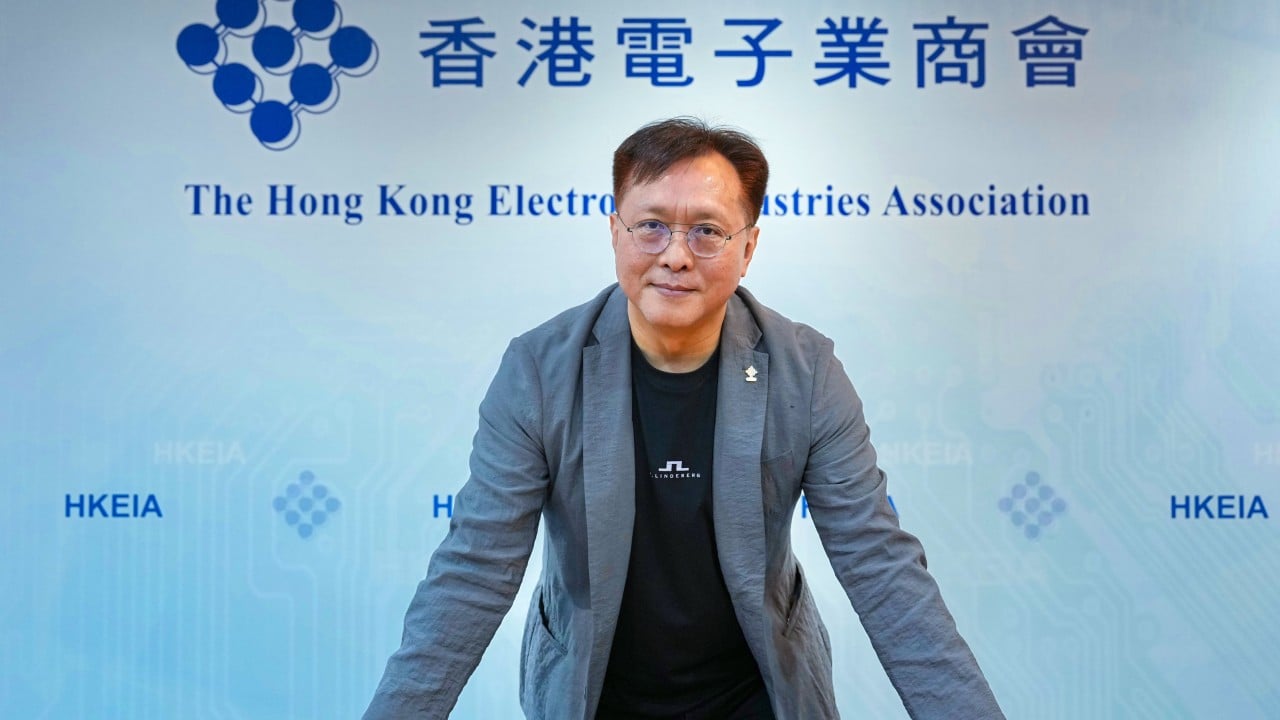
Capital formation efficiency in modern exchanges relies entirely on the minimization of transactional and regulatory friction between early-stage risk capital and scalable enterprise models. When the Hong Kong Electronics and Information Industry Association (HKEIA) recently argued that Hong Kong must ease listing rules to attract angel funds and start-ups, the core diagnosis was accurate, but the underlying mechanics require rigorous deconstruction. The public equity market in Hong Kong functions as a liquidity engine heavily optimized for late-stage enterprises, conglomerates, and mainland giants. It was never architected to absorb the high-variance, low-information-density profile of early-stage technology firms or the micro-ticket allocation structures typical of angel networks.
To understand why traditional listing frameworks fail to capture early-stage capital inflows, one must examine the cost function of public market compliance versus the return distribution of early-stage assets. Public exchanges impose fixed regulatory overheads—auditing, continuous disclosure, corporate governance mandates, and legal compliance—that scale inversely with enterprise size. For an early-stage start-up or an angel fund managing a concentrated portfolio of pre-revenue entities, these fixed costs consume capital that should otherwise be deployed toward product-market fit or technical validation.
Furthermore, angel investors operate on a power-law return distribution. A tiny fraction of investments generate exponential returns that offset the total loss of the rest. Public markets, by contrast, are governed by fiduciary standards, institutional risk aversion, and quarterly disclosure rhythms that penalize volatility. When an exchange attempts to court angel capital using frameworks built for mature enterprises, a structural mismatch occurs. The liquidity provided by public markets requires standardized information and predictable cash flows, whereas early-stage start-ups offer none of these attributes.
Evaluating the friction points reveals three structural failures within the current exchange architecture:
The Information Asymmetry Penalty. Public markets demand continuous, verified financial metrics. Early-stage start-ups operate in environments of high strategic pivot frequency where historical financial data has zero predictive power regarding future enterprise value. Requiring rigid reporting standards forces these firms to either misallocate resources toward compliance or remain entirely outside the public venue.
The Valuation Liquidity Premium Deficit. Angel funds require secondary market liquidity to recycle capital into new ventures. Without a viable pipeline from private seed rounds to public micro-caps, early investors face extended lock-up periods. When the exchange lacks low-threshold listing tiers, this liquidity pipeline breaks down, starving subsequent seed rounds of returning capital.
The Underwriting Cost Barrier. Traditional underwriting and sponsorship requirements in primary markets impose prohibitive fees for small-capitalization offerings. The economics of investment banking advisory services make it unprofitable to underwrite offerings below specific capital thresholds, creating a structural exclusion zone for high-growth tech start-ups seeking initial public funding.
To resolve these friction points without compromising market integrity, structural interventions must target the regulatory architecture rather than relying on superficial marketing campaigns or generic incentive grants.
The first necessary adjustment involves the creation of a segmented, tiered exchange subsidiary explicitly designed for high-growth, high-risk assets. This tier must decouple continuous disclosure requirements from the rigid frameworks applied to main board listings. Instead of quarterly financial reporting, firms in this specialized segment should report on milestones, burn rate efficiency, and technological deployment metrics that genuinely reflect their operational progress.
The second intervention requires the modernization of sponsorship rules for small-cap offerings. By introducing algorithmic or streamlined underwriting pathways that reduce reliance on legacy investment banking gatekeepers, the cost of capital formation for small issues drops significantly. This mirrors the evolution seen in alternative financing vehicles, but brings those assets under the regulatory oversight and transparency of a recognized exchange.
Critics of relaxed listing standards frequently cite investor protection concerns, arguing that lowering barriers invites market manipulation, fraudulent shell companies, and excessive retail exposure to high-risk instruments. This critique, while valid regarding retail capital, misunderstands the nature of modern risk segregation. Market integrity is not maintained by locking out early-stage companies entirely; it is maintained by implementing strict institutional investor qualification thresholds, mandatory lock-up periods for founders, and transparent risk disclosures.
When institutional capital and sophisticated angel syndicates are given a clear, compliant playground within a public exchange framework, price discovery improves. The current alternative—where early-stage financing remains entirely sequestered in opaque private markets—transfers systemic opacity from the public eye into private silos where retail and secondary investors have zero visibility until late-stage valuations have already peaked.
The strategic play for Hong Kong's exchange operators and regulators is clear. They must stop treating market entry as a binary gate where an enterprise is either mature enough for the Main Board or entirely excluded from public capital mechanisms. By constructing a dedicated, high-transparency, low-friction sub-exchange specifically engineered for early-stage technology and innovation assets, the market can capture the front-end of the venture capital lifecycle. The objective is not to lower standards of integrity, but to modernize the mechanics of access so that capital formation begins at the inception of growth rather than at its mature plateau.